Choosing between the new and old tax regime can significantly affect how much income tax you pay. For FY 2024-25, the comparison is especially important because the new regime became the default framework, while the old regime continued to offer a wider range of deductions and exemptions.
The right choice is not automatically the regime with the lowest tax rate. It depends on your salary structure, investments, home-loan benefits, insurance premiums, eligible deductions, and total taxable income. This guide compares the income tax slabs 2024-25 under both regimes and explains how to make a practical decision.
Understanding FY 2024-25 and the Correct Assessment Year
A common source of confusion is the difference between the financial year and assessment year.
For income earned from 1 April 2024 to 31 March 2025, the relevant period is:
- Financial Year (FY): 2024-25
- Assessment Year (AY): 2025-26
The tax slabs discussed in this article apply to income earned during FY 2024-25 and assessed in AY 2025-26.
The new tax regime remains the default regime for eligible individual taxpayers, although eligible taxpayers can choose the old regime subject to the applicable rules.
New Tax Regime Income Tax Slabs for FY 2024-25
Under the new tax regime for FY 2024-25, income is taxed using the following slab structure:
| Taxable Income | Tax Rate |
|---|---|
| Up to ₹3,00,000 | Nil |
| ₹3,00,001 to ₹7,00,000 | 5% |
| ₹7,00,001 to ₹10,00,000 | 10% |
| ₹10,00,001 to ₹12,00,000 | 15% |
| ₹12,00,001 to ₹15,00,000 | 20% |
| Above ₹15,00,000 | 30% |
These rates apply progressively. Your entire income is not taxed at the rate of the highest slab you enter. Instead, each portion of taxable income is taxed according to the relevant slab.
Higher Standard Deduction for Salaried Taxpayers
For FY 2024-25, eligible salaried taxpayers and pensioners can claim a ₹75,000 standard deduction under the new tax regime.
This means a person earning salary income may have a lower taxable income after the standard deduction is applied. The benefit can make the new regime more attractive for taxpayers who do not claim substantial deductions elsewhere.
Section 87A Rebate Under the New Regime
A resident individual with total income up to ₹7 lakh may qualify for a rebate under Section 87A, subject to the applicable conditions.
The maximum rebate under the new regime is ₹25,000 for the relevant threshold. As a result, the tax liability before cess can become nil for an eligible taxpayer whose total income does not exceed ₹7 lakh.
This rebate is one reason the new regime can be particularly attractive for taxpayers with modest taxable income.
Old Tax Regime Income Tax Slabs for FY 2024-25
The old tax regime follows a different slab structure and allows taxpayers to use a broader range of deductions and exemptions.
For individuals below 60 years of age:
| Taxable Income | Tax Rate |
| Up to ₹2,50,000 | Nil |
| ₹2,50,001 to ₹5,00,000 | 5% |
| ₹5,00,001 to ₹10,00,000 | 20% |
| Above ₹10,00,000 | 30% |
The old regime continues to provide special basic exemption limits for eligible resident senior and super-senior citizens.
Standard Deduction in the Old Regime
Eligible salaried taxpayers and pensioners can claim a ₹50,000 standard deduction under the old regime.
The lower standard deduction compared with the new regime does not automatically make the old regime less beneficial. The old regime may still produce a lower final tax liability if you claim substantial exemptions and deductions.
Section 87A Rebate in the Old Regime
For eligible resident individuals under the old regime, the Section 87A rebate applies where total income does not exceed ₹5 lakh, subject to the statutory conditions.
The maximum rebate is ₹12,500.
New vs Old Tax Regime: Side-by-Side Comparison
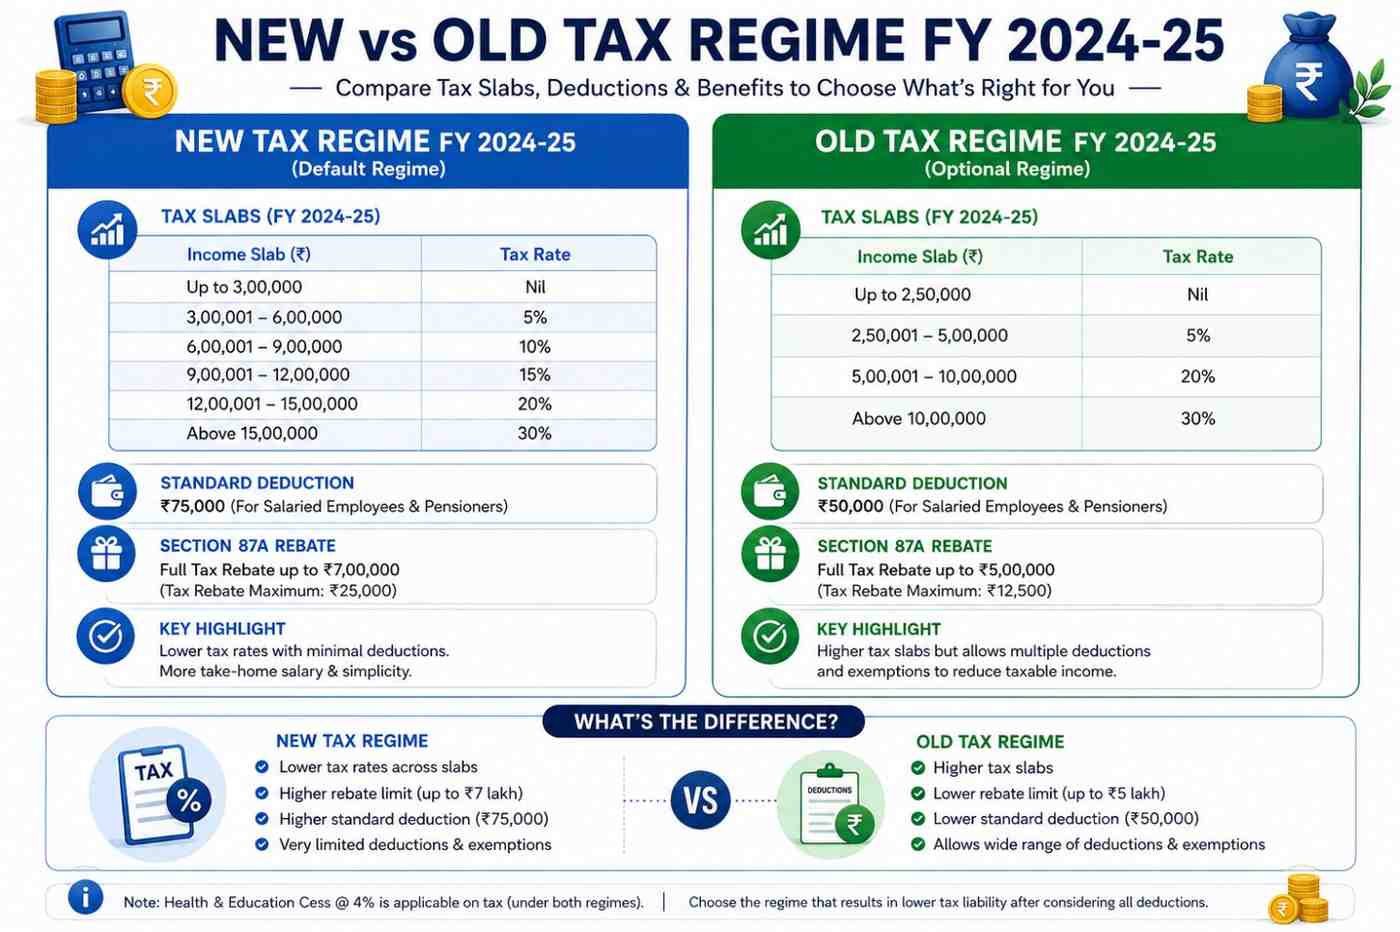
| Feature | New Tax Regime | Old Tax Regime |
| Basic exemption limit | ₹3 lakh | ₹2.5 lakh for most individuals |
| Tax rates | Generally lower across several slabs | Higher rates after lower slabs |
| Standard deduction | ₹75,000 for eligible salary/pension income | ₹50,000 for eligible salary/pension income |
| Section 80C benefits | Generally not available | Available if eligible |
| Home loan interest benefits | Limited based on applicable provisions | Available subject to conditions |
| HRA exemption | Generally not available | Available if eligible |
| LTA exemption | Generally not available | Available if eligible |
| Other deductions | Limited | Wider range available |
| Default regime | Yes | Must be selected where applicable |
| Best suited for | Taxpayers with fewer deductions | Taxpayers using substantial exemptions and deductions |
The central trade-off is simple: the new regime offers lower rates and simpler taxation, while the old regime can reward disciplined tax planning through deductions and exemptions.
Deductions and Exemptions: Where the Real Difference Appears
The tax slab comparison alone does not tell the complete story.
Section 80C Investments
Under the old regime, eligible taxpayers may claim deductions for qualifying investments and payments under Section 80C, subject to the prescribed limit and conditions.
Common examples can include:
- Employee Provident Fund contributions
- Public Provident Fund investments
- Eligible life insurance premiums
- ELSS investments
- Principal repayment on an eligible home loan
- Eligible tuition fees
These benefits can substantially reduce taxable income for taxpayers who already make qualifying investments.
Section 80D Health Insurance
Eligible health insurance premiums may qualify for deductions under Section 80D in the old regime, subject to applicable limits and conditions.
This is important for individuals who pay premiums for themselves, their spouse, children, or eligible parents.
House Rent Allowance
Salaried taxpayers receiving HRA may benefit from an exemption under the old regime if they satisfy the applicable conditions.
For a taxpayer paying significant rent in a high-cost city, HRA can materially change the old-versus-new regime calculation.
Home Loan Interest
The old regime may allow eligible deductions for home-loan interest and principal repayment under the relevant provisions.
For homeowners with significant eligible housing deductions, the old regime can remain competitive despite its higher headline tax rates.
Which Tax Regime Is Better for Salaried Employees?
There is no universal winner.
The new tax regime often works well for salaried employees who:
- Do not have major tax-saving investments
- Do not claim HRA
- Have limited home-loan deductions
- Prefer a simpler tax structure
- Do not want to make investments primarily for tax-saving purposes
The old regime may be more suitable for employees who:
- Fully use eligible Section 80C deductions
- Claim HRA exemption
- Pay eligible health insurance premiums
- Have qualifying home-loan benefits
- Use other available exemptions and deductions
The most important step is to compare the actual final tax liability, not just the tax rates.
A Simple Way to Compare Your Tax Liability
Follow this practical approach before choosing a regime.
Step 1: Calculate Your Gross Income
Add income from all relevant sources, such as:
- Salary
- Pension
- House property
- Business or professional income
- Capital gains
- Other taxable income
Different types of income can have special tax treatment, so do not assume every rupee is taxed according to normal slab rates.
Step 2: Calculate Taxable Income Under the Old Regime
Reduce eligible exemptions and deductions from gross income according to the applicable rules.
Potential benefits may include:
- Standard deduction
- HRA exemption
- Section 80C
- Section 80D
- Eligible home-loan deductions
- Other qualifying deductions
Step 3: Calculate Taxable Income Under the New Regime
Apply only the deductions and exemptions available under the new regime.
For FY 2024-25, eligible salaried taxpayers should account for the ₹75,000 standard deduction.
Step 4: Apply the Correct Slab Rates
Calculate tax progressively under each regime.
Do not forget:
- Section 87A rebate, where applicable
- Surcharge, where applicable
- Health and education cess
The Income Tax Department recommends comparing liability under both systems because the better option depends on individual circumstances.
Example: How the Decision Can Change
Consider two taxpayers with similar gross income.
Taxpayer A: Minimal Deductions
Suppose the taxpayer:
- Does not claim HRA
- Has no major home-loan deduction
- Makes limited tax-saving investments
- Has only standard eligible salary deductions
The new regime may be more attractive because lower slab rates and the higher standard deduction can outweigh the benefits available under the old regime.
Taxpayer B: High Eligible Deductions
Now consider a taxpayer who:
- Uses eligible Section 80C investments
- Claims HRA exemption
- Pays health insurance premiums
- Has qualifying home-loan deductions
The old regime may reduce taxable income enough to offset its higher slab rates.
This illustrates why the answer to “Which regime saves more tax?” depends on the individual calculation.
Common Mistakes When Choosing a Tax Regime
Looking Only at the Highest Tax Rate
A 30% top slab does not mean your entire income is taxed at 30%.
India follows progressive taxation for normal slab income. Always calculate tax slab by slab.
Choosing the Old Regime Only for Section 80C
Tax-saving investments should support your broader financial goals.
Do not lock money into unsuitable investments simply to claim a deduction. First compare the actual tax savings with the investment's liquidity, risk, returns, and suitability.
Ignoring the Standard Deduction Difference
For FY 2024-25, the standard deduction available to eligible salaried taxpayers differs between the regimes.
That difference should be included before comparing the final numbers.
Assuming You Can Always Change Freely
Taxpayers without business or professional income generally have greater flexibility to choose the regime in their return, subject to applicable filing rules.
For taxpayers with business or professional income, switching rules are more restrictive and may involve Form 10-IEA.
Forgetting Cess and Surcharge
The slab calculation is not always the final tax amount.
Health and education cess and, for higher incomes, surcharge can increase the final liability.
How to Choose the Best Tax Regime for FY 2024-25
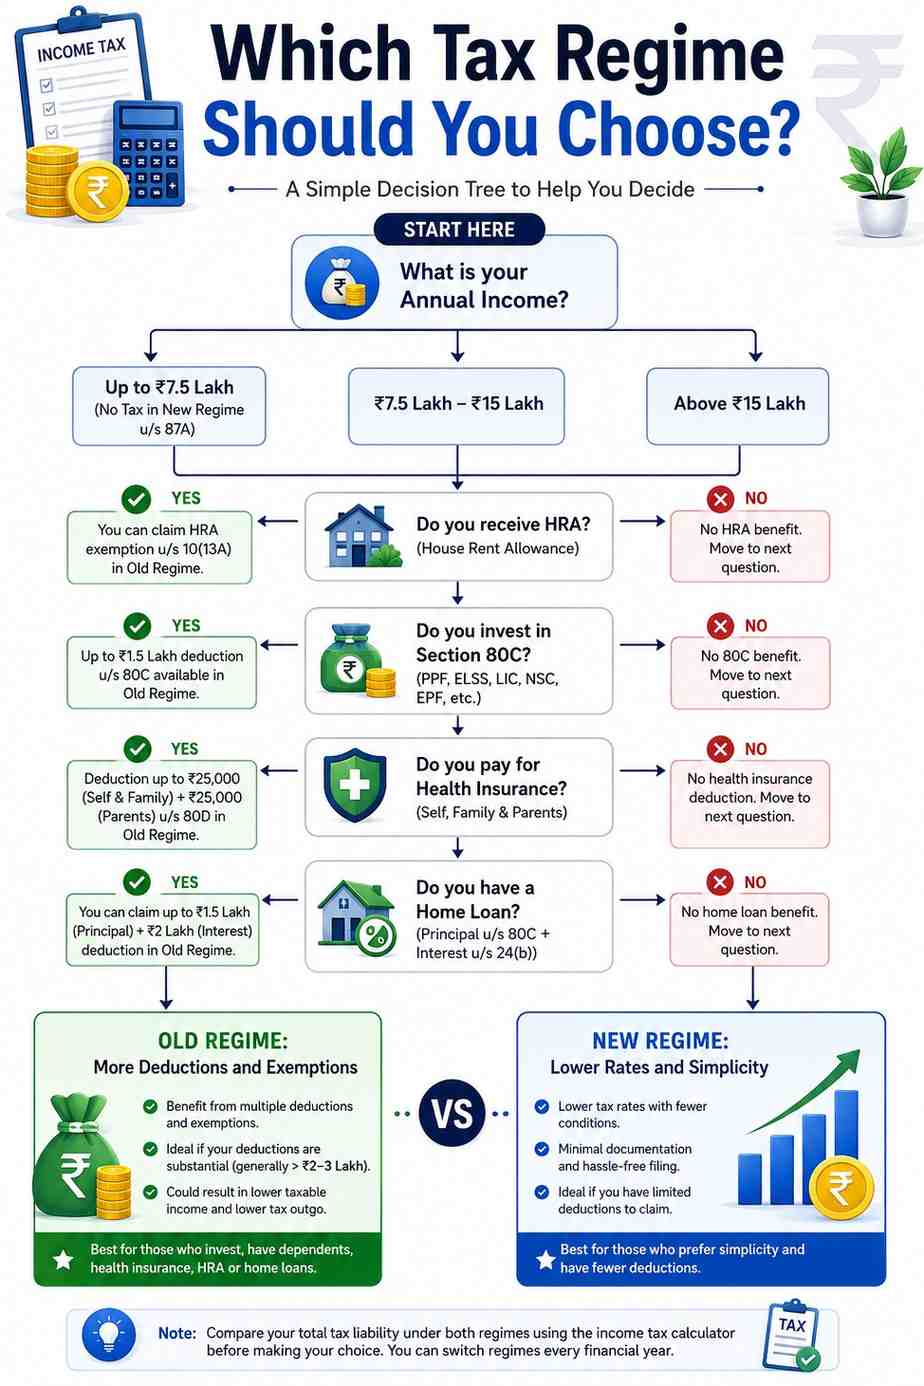
Use this decision framework.
Choose the new tax regime if your deductions and exemptions are relatively low and you value simplicity.
Choose the old tax regime if your eligible deductions and exemptions are substantial enough to meaningfully reduce taxable income.
Before making a decision, prepare a list of:
- Annual gross income
- Salary components
- HRA eligibility
- Section 80C investments
- Health insurance premiums
- Home-loan interest and principal benefits
- Other eligible deductions
- Special-rate income, such as certain capital gains
Then calculate both outcomes using the same income data.
The regime with the lower tax liability is generally the financially efficient choice, provided it also fits your long-term financial plan.
Important Rules About Selecting a Tax Regime
The new tax regime is the default regime for eligible taxpayers under the applicable provisions. Eligible taxpayers may opt for the old regime, but the method and flexibility can differ depending on whether they have business or professional income.
For taxpayers without business income, the choice can generally be made each year while filing the return within the applicable deadline.
Taxpayers with business or professional income should pay particular attention to the rules for opting out and switching, including the applicable Form 10-IEA requirements.
Because tax rules can involve exceptions, taxpayers with complex income structures may benefit from professional advice before making an irreversible or restrictive choice.
FAQ
What are the income tax slabs for FY 2024-25 under the new regime?
For FY 2024-25, the new regime has slabs of nil up to ₹3 lakh, followed by 5%, 10%, 15%, 20%, and 30% rates across progressively higher income ranges. The highest normal slab rate applies to income above ₹15 lakh.
What are the old tax regime slabs for FY 2024-25?
For most individuals below 60 years, the old regime provides nil tax up to ₹2.5 lakh, 5% from ₹2.5 lakh to ₹5 lakh, 20% from ₹5 lakh to ₹10 lakh, and 30% above ₹10 lakh. Different basic exemption limits apply to eligible senior and super-senior citizens.
Is the new tax regime better than the old tax regime?
It depends on your deductions and exemptions. The new regime may benefit taxpayers with fewer deductions, while the old regime may be better for those claiming substantial eligible benefits such as HRA, Section 80C, Section 80D, and qualifying home-loan deductions.
Can I claim Section 80C in the new tax regime?
Most common Section 80C deductions are not available in the new regime. Certain specified exceptions may apply under tax law, so taxpayers should review the exact provision relevant to their income and investment.
What is the Section 87A rebate limit under the new regime for FY 2024-25?
For eligible resident individuals, the new regime provides a rebate where total income does not exceed ₹7 lakh, subject to applicable statutory conditions. The maximum rebate is ₹25,000.
Which tax regime is better for a salary of ₹10 lakh?
The answer depends on your deductions. If you have limited exemptions and deductions, the new regime may often be competitive. If you claim significant eligible HRA, Section 80C, health insurance, and housing deductions, the old regime may produce a lower tax liability.
Final Thoughts
The income tax slabs 2024-25 comparison is not simply about choosing lower tax rates. The new regime focuses on lower rates and simpler compliance, while the old regime rewards taxpayers who can legitimately use eligible deductions and exemptions.
For efficient tax planning, calculate your tax under both regimes using your actual income and eligible claims. Avoid choosing investments purely to save tax, and avoid selecting the new regime without checking whether your existing deductions make the old regime more valuable. The smartest choice is the one that minimizes your lawful tax burden while still supporting your broader financial goals.
Write a comment