Jab bhi humein kisi financial emergency ka samna karna padta hai, toh gold loan ek popular aur reliable option hota hai. Sona, ek valuable asset hone ke saath-saath, apni liquidity aur secure nature ke liye jaana jata hai. Is blog mein hum discuss karenge ki gold loan kaise liya jata hai aur ROI yani Return on Investment kaise calculate hota hai. Agar aap gold loan lene ka soch rahe hain ya iske baare mein zyada jankari chahte hain, toh yeh article aapke liye kaafi useful hoga.
Gold Loan Kya Hota Hai?
Gold loan ek secured loan hai jo aapke sone ko girvi rakhkar diya jata hai. Aap apne sone ki purity aur weight ke hisaab se bank ya Non-Banking Financial Company (NBFC) se loan prapt kar sakte hain. Yeh loan generally short-term hota hai, jise aap specific tenure ke dauran repay karte hain, aur is par ek interest rate lagti hai, jo aapke loan amount ke saath calculate hoti hai.
Gold Loan Ka Process Kaisa Hota Hai?
Gold loan lene ka process kaafi straightforward hota hai. Aapko apne sone ko lekar bank ya NBFC ke paas jana hota hai, jahan uska valuation kiya jata hai. Iske baad, aapko us sone ke current market value ke hisaab se loan amount diya jata hai.
- Eligibility Check: Gold loan lene ke liye aapko minimum 18 saal ka hona zaroori hai. Aapke paas kam se kam 18 karat purity wala sona hona chahiye.
- Document Submission: Identity proof (Aadhaar card, Voter ID, etc.) aur address proof (Electricity bill, ration card, etc.) ki zaroorat hoti hai. Sone ke ownership documents bhi submit karne hote hain.
- Loan Application: Aap apni nearest bank ya NBFC mein apply kar sakte hain. Aajkal kai institutions online application bhi accept karte hain.
- Sone Ka Valuation: Sone ki purity aur weight ke basis par uska valuation kiya jata hai. Aapko us valuation ke 75% tak loan mil sakta hai.
- Loan Disbursement: Jaise hi aapka loan approve hota hai, aapko loan amount aapke bank account mein mil jata hai.
Gold Loan Ki Interest Rate Aur ROI Kaise Calculate Hoti Hai?
Gold loan par interest rate yani ROI ko samajhna zaroori hai. Generally, gold loan par interest rate fixed hoti hai, lekin kai baar aapko floating rate bhi mil sakti hai. ROI calculate karte waqt kai factors ko consider kiya jata hai:
- Loan Amount: Aapne kitna loan liya hai, us par depend karta hai ki aapko interest kitna lagega.
- Loan Tenure: Loan ki duration jitni zyada hogi, ROI utni hi zyada hogi.
- Market Conditions: Gold ke current market price aur economic conditions bhi ROI par impact karte hain.
Interest rate do prakar ki hoti hai:
- Fixed Interest Rate: Isme aapka interest rate loan tenure ke dauran same rehta hai.
- Floating Interest Rate: Yeh market ke according change hoti rehti hai, jisse aapka interest kam ya zyada ho sakta hai.
Gold Loan Ka ROI (Return on Investment) Kaise Samjhein?
Gold loan ka ROI samajhna isliye zaroori hai kyunki yeh aapke overall loan cost ko affect karta hai. ROI basically ek indicator hai jo batata hai ki aap apne investment par kitna return expect kar sakte hain. Gold loan ke case mein, ROI ko samajhne ke liye aapko loan ke overall cost aur aapki repayment capacity par focus karna hoga.
Example: Agar aapne ₹1,00,000 ka gold loan liya hai 10% interest rate par for 1 year, toh aapka total repayment ₹1,10,000 hoga. Isme ₹10,000 aapka interest amount hoga, jo aapke ROI ko reflect karta hai.
Gold Loan Lene Ke Fayde Aur Nuksan
Gold loan lene se pehle uske fayde aur nuksan ko samajhna important hai. Yeh table aapko gold loan ke benefits aur drawbacks ke baare mein detail information dega:
| Fayde (Advantages) | Nuksan (Disadvantages) |
|---|---|
| Quick Disbursement: Loan approval fast hota hai. | Sona Girvi Rakhna Padta Hai: Agar aap loan repay nahi karte, toh sona bank ke paas reh jata hai. |
| Low Interest Rates: Compared to personal loans, interest rate kam hota hai. | Repayment Issues: Agar aap timely repayment nahi karte, toh aapke sone ko forfeiture kiya ja sakta hai. |
| Minimal Documentation: Documentation kaafi simple hota hai. | Gold Value Dependency: Loan amount sone ki market value par depend karta hai. |
| No Credit Score Requirement: Aapke credit score ka itna impact nahi hota. | Market Fluctuations: Gold ki price down ho sakti hai jo loan repayment par impact daalti hai. |
| Flexible Repayment Options: Aap apne hisaab se EMI ya bullet payment choose kar sakte hain. | Short-Term Solution: Gold loan short-term financial needs ke liye better hai, lekin long-term commitments ke liye nahi. |
Gold Loan Vs. Personal Loan: Kaunsa Behtar?
Kai logon ke dimaag mein yeh sawal aata hai ki gold loan aur personal loan mein se kaunsa option better hai? Dono loan ke apne advantages aur disadvantages hain, jo niche diye gaye comparison table mein clearly dikhaye gaye hain:
| Feature | Gold Loan | Personal Loan |
|---|---|---|
| Collateral | Required (Gold) | Not Required |
| Interest Rate | Lower (ROI on Gold Loan) | Higher |
| Loan Amount | Based on Gold Valuation | Based on Income and Credit Score |
| Disbursement Time | Quick | Takes Time |
| Risk | Risk of Losing Gold if Default | No Collateral Risk |
Gold Loan Kaise Repay Karein?
Gold loan ko repay karne ke kai tarike hote hain, jo aap apni financial situation ke hisaab se choose kar sakte hain. Neeche kuch common repayment options diye gaye hain:
- EMI: Isme aap har mahine ek fixed amount pay karte hain, jo principal aur interest dono ko include karta hai.
- Bullet Repayment: Aap loan tenure ke end mein pura amount ek saath pay kar sakte hain.
- Interest-Only Payment: Isme aap loan tenure ke dauran sirf interest pay karte hain aur tenure ke end mein principal amount pay karte hain.
Gold loan lene se pehle sirf interest rate dekhna kaafi nahi hota. Aapko yeh bhi samajhna chahiye ki loan ki actual cost kitni hogi, kitna total repayment karna padega aur aapki financial situation par iska kya impact padega. Isi context mein kai log Gold Loan Ka ROI samajhna chahte hain.
Lekin yahan ek important baat hai: gold loan mein “ROI” shabd kabhi-kabhi galat context mein use hota hai. Traditional investment mein ROI ka matlab hota hai Return on Investment, yani investment se kitna profit mila. Gold loan mein borrower ke liye interest amount technically return nahi, balki loan ki cost hoti hai. Isliye gold loan ko samajhne ke liye interest rate, total interest, charges aur repayment capacity par focus karna zyada useful hai.
Gold Loan Mein ROI Ka Actual Meaning Kya Hai?
Investment ke case mein ROI ek formula se calculate hota hai:
ROI = (Net Profit ÷ Investment Cost) × 100
For example, agar aap ₹1 lakh invest karte hain aur ₹10,000 ka profit milta hai, to ROI 10% ho sakta hai.
Gold loan mein situation alag hoti hai. Yahan aap apna paisa invest nahi kar rahe, balki apne gold ko collateral ke roop mein rakhkar loan le rahe hain. Isliye borrower ke perspective se sabse important numbers hain:
- Loan amount
- Annual interest rate
- Loan tenure
- Processing fees aur other charges
- Repayment structure
- Total amount payable
Agar koi gold loan context mein ROI bol raha hai, to aksar practical meaning loan par effective cost ya interest burden hota hai.
Interest Rate Aur ROI Mein Difference
Interest rate batata hai ki lender aapse borrowed amount par kitna annual charge karega. ROI investment ki profitability measure karta hai.
Isliye agar aap ₹1,00,000 ka gold loan 10% annual interest rate par lete hain, to 10% ko investment return samajhna technically sahi nahi hoga. Aapke liye yeh 10% borrowing cost hai.
Gold Loan Ki Total Cost Kaise Samjhein?
Gold loan ki cost samajhne ke liye sirf advertised interest rate par depend nahi karna chahiye. Actual repayment amount kai factors se influence hota hai.
Principal Amount
Principal woh actual loan amount hai jo aap lender se borrow karte hain.
Agar aapko ₹1,00,000 ka loan sanction hua hai, to ₹1,00,000 aapka principal hai.
Interest Amount
Simple example mein:
Interest = Principal × Interest Rate × Time
Agar:
- Principal = ₹1,00,000
- Interest rate = 10% per year
- Tenure = 1 year
To interest hoga:
₹1,00,000 × 10% × 1 = ₹10,000
Total repayment:
₹1,00,000 + ₹10,000 = ₹1,10,000
Yani ek simple annual-interest example mein aapko ₹10,000 interest cost ke roop mein dena hoga.
Additional Charges
Actual gold loan cost mein ye charges bhi ho sakte hain:
- Processing fee
- Valuation charges
- Documentation charges
- Late payment charges
- Penal interest
- Renewal charges
- Auction-related charges, agar repayment default ho
Har lender ki fee structure alag ho sakti hai. Isliye loan agreement aur Key Fact Statement ko dhyan se padhna zaroori hai.
₹1 Lakh Gold Loan Ka Detailed Example
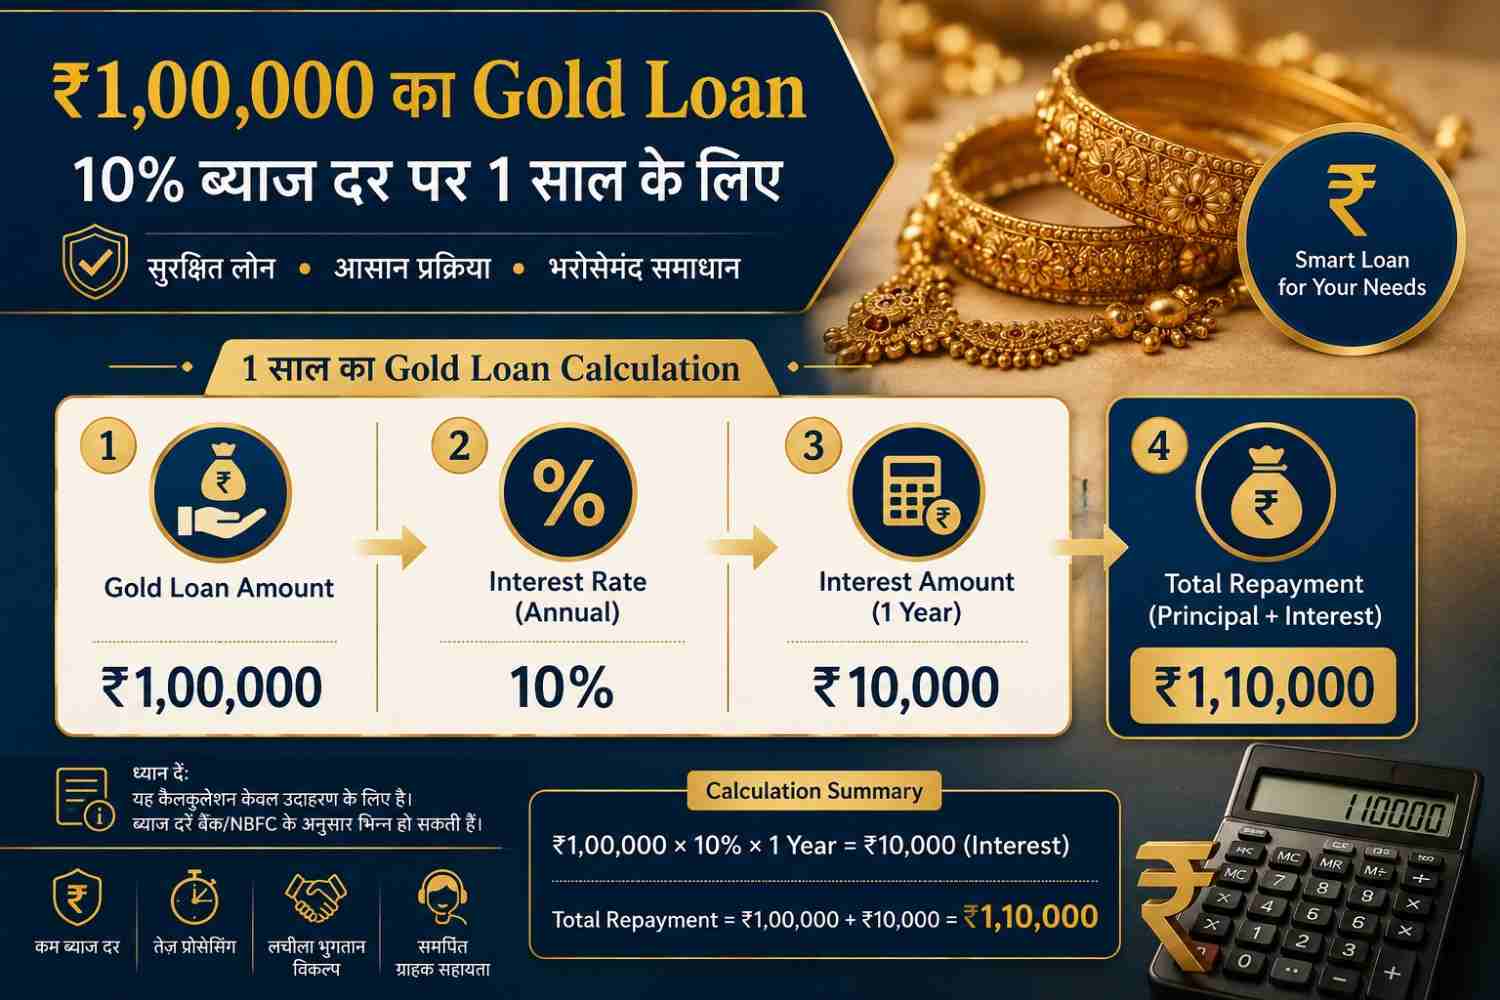
Maan lijiye aapne ₹1,00,000 ka gold loan liya hai.
| Detail | Amount |
|---|---|
| Loan Amount | ₹1,00,000 |
| Interest Rate | 10% per year |
| Tenure | 12 months |
| Estimated Interest | ₹10,000 |
| Total Repayment | ₹1,10,000 |
Yeh example simple interest assumption par based hai.
Lekin real gold loan repayment plan different ho sakta hai. Kuch loans mein monthly EMI hoti hai, kuch mein regular interest payment aur principal maturity par dena hota hai, jabki kuch short-term bullet repayment structure follow kar sakte hain.
Isliye same interest rate hone ke bawajood total cost repayment method ke according change ho sakti hai.
Gold Loan Interest Rate Kaise Calculate Karein?
Gold loan interest calculation ko samajhne ke liye aapko annual rate ko repayment period ke context mein dekhna hoga.
Monthly Interest Example
Maan lijiye:
- Loan amount = ₹1,00,000
- Annual interest rate = 12%
Approximate monthly rate:
12% ÷ 12 = 1% per month
Ek mahine ka simple interest:
₹1,00,000 × 1% = ₹1,000
Agar principal poore period tak same rahe, to har month ka interest outstanding amount par calculate ho sakta hai. Lekin exact calculation lender ke interest method aur repayment structure par depend karegi.
Reducing Balance Method
EMI-based loans mein interest aksar outstanding principal par calculate hota hai. Jaise-jaise aap principal repay karte hain, outstanding balance kam hota hai.
Is situation mein total interest simple annual multiplication se alag ho sakta hai.
Isi liye loan compare karte waqt lender se repayment schedule lena useful hota hai.
Gold Loan Ka Effective Cost Kaise Compare Karein?
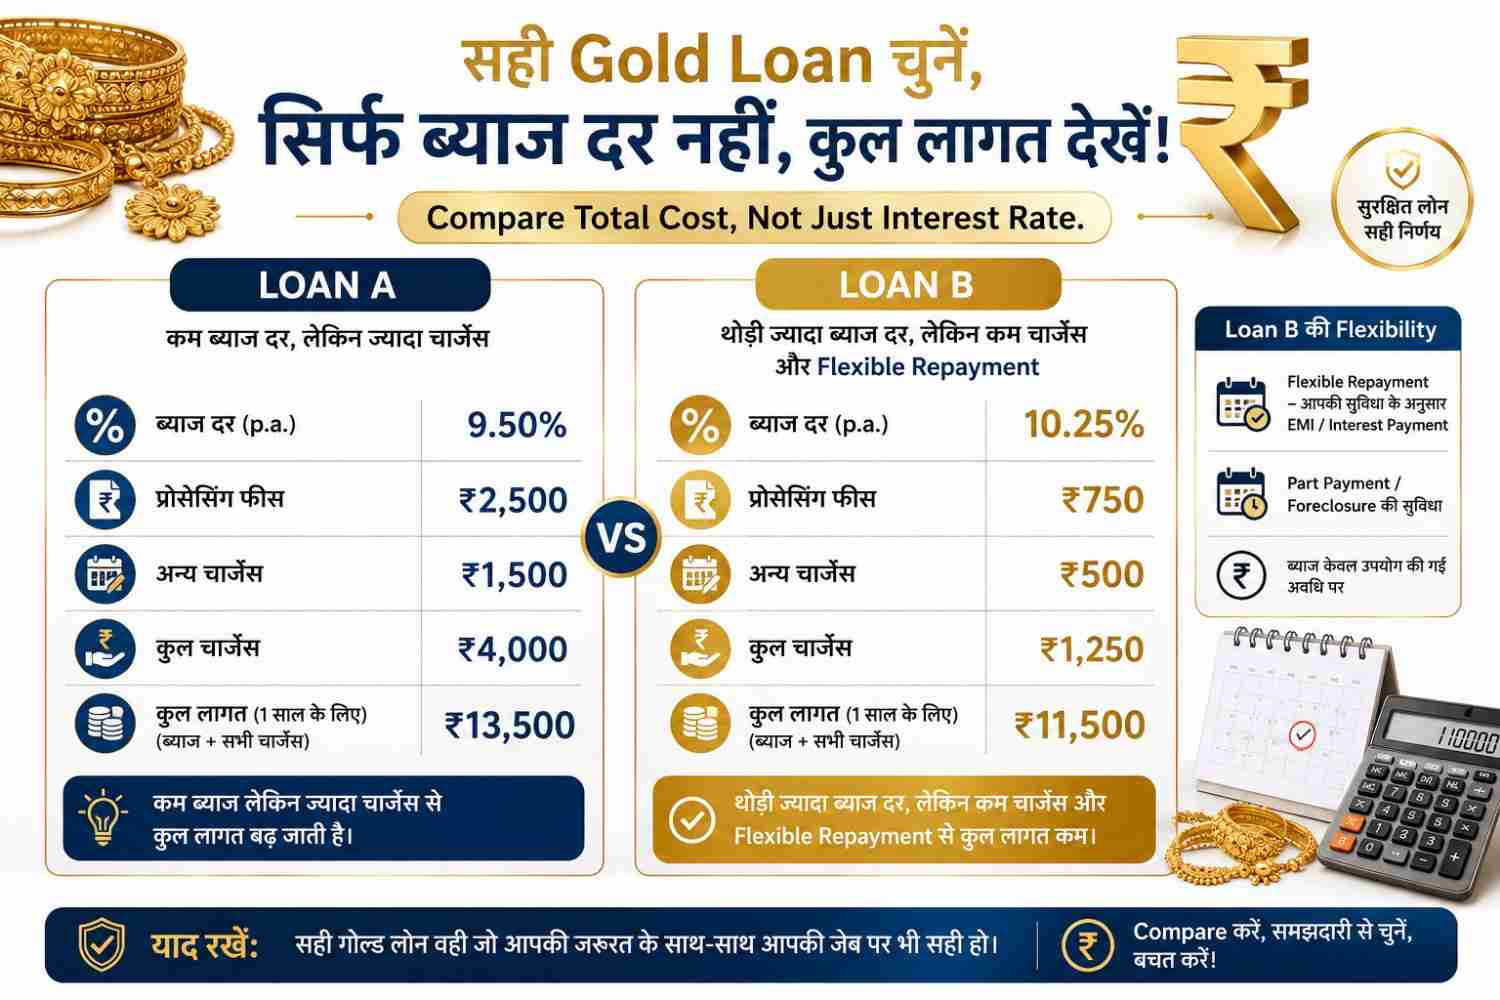
Do gold loans ko compare karne ke liye sirf “lowest interest rate” dekhna best approach nahi hai.
Maan lijiye:
Loan A:
Interest rate 9%, lekin processing aur other charges zyada hain.
Loan B:
Interest rate 10%, lekin charges kam hain aur prepayment flexible hai.
Short tenure ke liye Loan B kabhi-kabhi overall cost ke hisaab se better ho sakta hai.
Compare karte waqt yeh points dekhein:
- Annual interest rate
- Total interest payable
- Processing fee
- Other mandatory charges
- Late payment penalties
- Prepayment conditions
- Loan tenure
- EMI ya repayment schedule
- Renewal terms
Best gold loan woh nahi hota jo sirf advertisement mein lowest rate dikhaye. Best option woh hota hai jo aapki actual repayment requirement ke liye financially suitable ho.
Gold Loan Repayment Capacity Kyun Important Hai?
Gold loan lene ka decision tabhi practical hota hai jab repayment plan clear ho.
Loan lene se pehle khud se poochhein:
- Kya monthly income se repayment comfortably ho sakti hai?
- Kya emergency fund available hai?
- Kya income temporarily kam hone par bhi interest pay kar sakte hain?
- Kya loan ka purpose financially useful hai?
- Kya shorter tenure choose karne se total interest kam hoga?
Agar repayment capacity weak hai, to low interest rate bhi loan ko financially risky bana sakti hai.
Interest Payment Miss Hone Ka Impact
Late payment par additional charges lag sakte hain. Long delays ke case mein outstanding liability badh sakti hai.
Gold loan secured loan hota hai, isliye pledged gold lender ke security interest ka hissa hota hai. Default ki situation mein lender agreement aur applicable rules ke according recovery process initiate kar sakta hai.
Isliye gold loan ko “easy money” samajhkar nahi lena chahiye. Yeh ek secured financial obligation hai.
Gold Loan Lene Se Pehle Loan-to-Value Ko Samjhein
Gold loan mein lender aapke gold ki assessed value ke basis par loan amount decide karta hai.
Har gram gold ka market value directly loan amount nahi ban jata. Gold purity, lender valuation method aur applicable loan-to-value limits important hote hain.
Higher loan amount lena hamesha better nahi hota.
Agar aapko actual requirement ₹1 lakh ki hai, to sirf eligibility zyada hone ki wajah se ₹2 lakh loan lena unnecessary interest burden create kar sakta hai.
Smart borrowing ka simple rule hai:
Jitni zarurat ho, utna hi borrow karein.
Gold Loan Cost Kam Karne Ke Practical Tips
Shorter Tenure Consider Karein
Agar aap realistically loan jaldi repay kar sakte hain, shorter tenure total interest burden ko reduce kar sakta hai.
Lekin repayment pressure ko ignore nahi karna chahiye. Bahut aggressive tenure cash flow problem create kar sakta hai.
Extra Charges Compare Karein
Processing fee aur documentation charges loan ki effective cost badha sakte hain. Sanction se pehle complete fee breakup dekhein.
Repayment Mode Samjhein
EMI, monthly interest payment aur bullet repayment mein cash flow requirement alag hoti hai.
Apni income pattern ke according repayment option choose karein.
Late Payment Se Bachein
Penalty charges avoid karne ke liye payment due dates track karein aur possible ho to repayment ke liye dedicated funds rakhein.
Prepayment Rules Check Karein
Agar aap loan jaldi close karne ki planning kar rahe hain, prepayment conditions pehle samajh lein.
Common Mistakes Jo Borrowers Karte Hain
Gold loan compare karte waqt kuch common mistakes financial cost ko unnecessarily badha sakti hain.
Sirf Low Interest Rate Dekhna
Low headline rate ka matlab hamesha lowest total cost nahi hota.
Charges aur repayment conditions bhi matter karte hain.
Maximum Eligible Amount Borrow Karna
Zyada eligibility ko zyada requirement samajhna galat ho sakta hai.
Unnecessary borrowing ka matlab unnecessary interest cost.
Repayment Plan Ke Bina Loan Lena
Loan sanction hona aur loan comfortably repay kar pana do alag cheezein hain.
Income aur cash flow ke according plan banana zaroori hai.
Agreement Ko Ignore Karna
Interest calculation method, tenure, penalty aur auction-related terms jaise clauses important hote hain.
Signing se pehle documents padhna ek basic financial safety step hai.
Gold Loan Kab Financially Useful Ho Sakta Hai?
Gold loan kuch situations mein useful financing option ho sakta hai, especially jab short-term funds ki genuine requirement ho aur repayment source reasonably clear ho.
Possible use cases:
- Temporary business working capital
- Medical expenses
- Education-related urgent costs
- Seasonal cash-flow gaps
- Emergency financial requirements
Lekin gold loan ko risky speculation ya uncertain investments ke liye use karna carefully evaluate karna chahiye.
Agar borrowed money se expected return uncertain hai, to loan interest aur potential investment loss dono ka risk consider karna zaroori hai.
Gold Loan Ka ROI Samajhne Ka Best Approach
Agar aap “Gold Loan Ka ROI” calculate karna chahte hain, to is practical framework ka use karein:
Step 1: Loan amount note karein.
Step 2: Annual interest rate check karein.
Step 3: Loan tenure identify karein.
Step 4: Total interest estimate karein.
Step 5: All additional charges add karein.
Step 6: Total repayment amount calculate karein.
Step 7: Apni repayment capacity check karein.
Is approach se aap loan ko “return” ke perspective se nahi, balki actual financial cost ke perspective se samajh paayenge.
FAQ
Gold loan mein ROI ka kya matlab hota hai?
Traditional finance mein ROI ka matlab Return on Investment hota hai. Gold loan borrower ke liye zyada relevant concept interest cost aur total repayment amount hai. Isliye ROI ko loan ki effective cost ke context mein samajhna practical hota hai.
₹1 lakh gold loan par 10% interest kitna hoga?
Simple one-year example mein 10% annual interest par ₹1,00,000 ka interest ₹10,000 hoga. Total repayment ₹1,10,000 hoga, agar additional charges na hon aur simple interest assumption use kiya jaye.
Gold loan ka total repayment kaise calculate karein?
Basic calculation mein principal amount aur interest amount add kiya jata hai. Actual repayment nikalte waqt processing fees, penalties aur applicable charges bhi consider karne chahiye.
Kya lower interest rate wala gold loan hamesha better hota hai?
Zaroori nahi. Total charges, repayment flexibility, tenure aur penalties bhi compare karni chahiye. Overall cost dekhna zyada important hai.
Gold loan jaldi repay karne se interest bach sakta hai?
Loan structure ke according early repayment se interest cost kam ho sakti hai. Lekin exact benefit aur prepayment conditions lender ke terms par depend karte hain.
Gold loan lene se pehle sabse important kya check karein?
Interest rate ke saath total repayment, charges, tenure, repayment schedule, penalty rules aur apni repayment capacity zaroor check karein.
Conclusion
Gold Loan Ka ROI samajhne ka sabse practical tareeka yeh hai ki aap interest rate ko investment return na samjhein, balki loan ki total financial cost par focus karein. ₹1 lakh ka loan 10% annual interest par simple example mein ₹10,000 interest generate karega, lekin actual repayment additional charges aur loan structure ke according different ho sakta hai.
Gold loan lene se pehle total payable amount aur apni repayment capacity compare karein. Jitni zarurat ho utna borrow karein, repayment terms dhyan se padhein aur loan ko manageable cash-flow plan ke saath use karein.
Write a comment