The Pradhan Mantri Jan Dhan Yojana (PMJDY) is India’s flagship financial inclusion programme aimed at ensuring every household has access to formal banking and financial services. Launched in August 2014, the scheme has reached deep into rural and urban India, opening zero-balance bank accounts and providing insurance, pension, loans, and more.
In 2026, the scheme continues to evolve with expanded benefits and renewed government focus on widening its reach and impact, particularly through recent Budget 2026 proposals aimed at strengthening credit, insurance, and financial empowerment for citizens.
What Is PM Jan Dhan Yojana?
PMJDY is a nationwide financial inclusion mission designed to bring every Indian into the formal banking system. The main goal is to provide affordable access to banking services such as savings and deposit accounts, remittances, credit, insurance, and pension products.
Some core features of the scheme include:
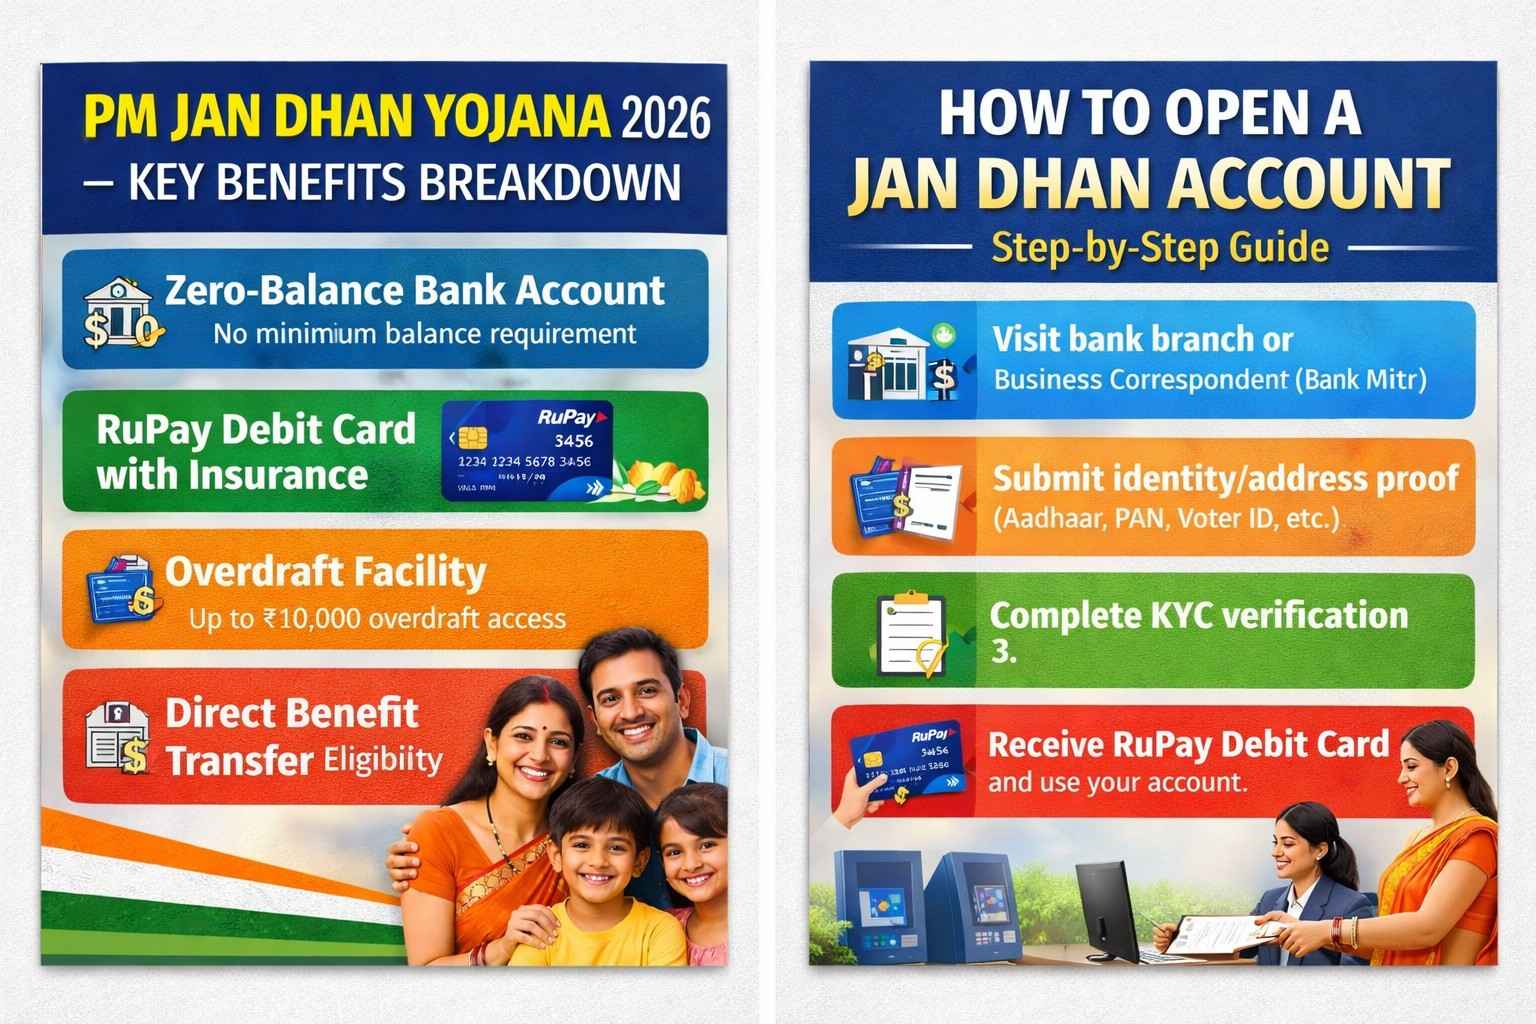
- Zero-balance savings accounts that require no minimum balance. PM Jan Dhan Yojana
- RuPay debit card with accident and life insurance coverage.
- Overdraft facility to eligible account holders.
- Linking Jan Dhan accounts with government benefits for Direct Benefit Transfer (DBT).
Key Benefits of PM Jan Dhan Yojana 2026
1. Zero-Balance Bank Account
Pradhan Mantri Jan Dhan Yojana (PMJDY) ke tahat log bina minimum balance maintain kiye bank account khol sakte hain. Is suvidha se kam aay wale aur banking services se door logon ke liye formal banking system se judna aasaan hua hai.
Zero-balance account ki wajah se account holder ko account mein paisa na hone par minimum balance maintain karne ka pressure nahi rehta. Iske madhyam se log savings, government benefits aur anya banking services ka upyog kar sakte hain. Is tarah Jan Dhan account financial inclusion ko badhava dene mein mahatvapurn bhoomika nibhata hai.
2. RuPay Debit Card With Insurance
Jan Dhan account holders ko RuPay debit card ki suvidha milti hai, jiske saath eligible account holders ke liye accidental insurance cover bhi linked ho sakta hai. Isse account holders ko banking services ke saath financial protection ka additional benefit milta hai.
- Accidental Insurance: Eligible RuPay cardholders ko scheme ke niyamon ke anusar accidental insurance cover mil sakta hai, jo kuch conditions ke tahat ₹2 lakh tak ho sakta hai.
- Life Insurance: Jan Dhan Yojana ke shuruaati phase mein eligible first-time account holders ke liye life insurance cover ka provision bhi tha, lekin is benefit ki eligibility aur availability specific scheme conditions par nirbhar karti hai.
Isliye RuPay debit card sirf cash withdrawal aur digital transactions ke liye hi useful nahi hai, balki eligible customers ko insurance-related financial security bhi provide kar sakta hai.
3. Overdraft Facility
Jan Dhan account holders ko kuch eligibility conditions poori karne par overdraft facility mil sakti hai. Is suvidha ke tahat eligible account holder apne account balance se adhik rashi, scheme ke nirdharit limit tak, zaroorat ke samay use kar sakta hai.
Satisfactory account operation aur anya prescribed conditions poori hone par ₹10,000 tak overdraft facility available ho sakti hai. Yeh suvidha achanak aane wali chhoti financial zarooraton ko poora karne mein madad kar sakti hai, khaaskar un logon ke liye jinke paas emergency ke samay turant funds available nahi hote.
Overdraft ek loan-like credit facility hoti hai, isliye iska upyog karne se pehle bank ki eligibility, repayment terms aur applicable charges ko samajhna zaroori ha
4. Direct Benefit Transfer (DBT) Eligibility
Jan Dhan accounts Direct Benefit Transfer (DBT) ke liye bhi mahatvapurn bhoomika nibhate hain. DBT ke madhyam se eligible beneficiaries ko sarkari subsidies, pensions aur anya welfare payments seedhe unke bank accounts mein transfer kiye ja sakte hain. Isse payment process ko zyada transparent aur convenient banane mein madad milti hai.
Direct bank transfer ke karan beneficiaries ko payment prapt karne ke liye unnecessary intermediaries par nirbhar nahi rehna padta. Saath hi, digital records hone se transactions ko track karna bhi aasaan hota hai. Is tarah DBT financial inclusion aur welfare delivery system ko majboot karne mein sahayak hai.
Halaanki, kisi particular government scheme ka DBT benefit prapt karne ke liye beneficiary ko us scheme ki eligibility conditions poori karni hoti hain aur account ko required process ke anusar link ya seed karna pad sakta hai.
5. Insurance and Pension Access
Jan Dhan account financial inclusion ko badhava dene ke saath-saath eligible account holders ko insurance, pension aur credit-related financial schemes tak pahunch banane mein bhi madad kar sakta hai. Inmein kuch pramukh schemes hain:
- Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY): Eligible individuals ko affordable life insurance cover pradan karne wali scheme.
- Pradhan Mantri Suraksha Bima Yojana (PMSBY): Eligible subscribers ko accident insurance cover dene wali low-cost scheme.
- Atal Pension Yojana (APY): Eligible subscribers ko retirement ke liye pension savings ka option provide karti hai.
- MUDRA Loans: Chhote businesses aur micro-enterprises ke liye institutional credit tak pahunch banane mein sahayak loan facility.
In schemes ki eligibility, age limits, premium, contribution aur benefits alag-alag hote hain. Isliye kisi bhi scheme ka benefit lene se pehle uski current eligibility conditions aur terms ko check karna zaroori hai.
6. Financial Inclusion & Literacy
Pradhan Mantri Jan Dhan Yojana (PMJDY) ka ek mahatvapurn uddeshya financial inclusion ko badhava dena hai. Iske madhyam se un logon ko formal banking system se jodne ka prayas kiya jata hai jo pehle banking aur anya financial services se door rahe hain.
PMJDY ke saath financial literacy par bhi zor diya jata hai, jisse log savings, banking transactions, insurance, pension, digital payments aur credit jaise financial services ko behtar tareeke se samajh saken. Financial awareness badhne se log apne paison se jude faisle adhik soch-samajhkar le sakte hain.
Formal banking services tak pahunch hone se logon ko har financial zaroorat ke liye informal lenders par nirbhar rehne ki zaroorat kam ho sakti hai. Is tarah PMJDY banking access badhane ke saath-saath logon ko formal financial system ka hissa banane mein bhi sahayak hai.
Eligibility Criteria for Opening a Jan Dhan Account
To open a PM Jan Dhan Yojana account, you need to meet the following basic eligibility:
- You should be an Indian citizen.
- Age 10 or above (minors aged 10+ can open with a guardian managing the account until 18).
- No prior bank account is required, making it ideal for first-time users.
- Non-Resident Indians (NRIs) are generally not eligible.
Documents like Aadhaar and PAN are typically used for KYC, but low-risk KYC options may allow account opening even without full documentation at the outset.
How to Apply for a Jan Dhan Account
Opening a Jan Dhan account is straightforward:
- Visit any bank branch or Bank Mitr (Business Correspondent) outlet.
- Submit basic identity and address proof (Aadhaar, PAN, voter ID, etc.).
- Complete KYC verification.
- Receive your RuPay debit card and start using the account.
Note: Accounts must remain active and have at least one transaction periodically to maintain insurance and overdraft benefits. Recent government efforts are focused on re-KYC drives to keep dormant accounts active.
Latest Updates for 2026
Government Clarification on Inactive Accounts
Recent media reports claimed banks might close inactive Jan Dhan accounts. However, the Department of Financial Services has clarified that no mandate exists to shut dormant accounts, and instead, banks are promoting awareness and re-KYC campaigns to keep accounts active.
Focus in Budget 2026
The Union Budget 2026 is placing renewed emphasis on Jan Dhan accounts with potential enhancements for women’s financial empowerment:
- Expanded credit and insurance access through Jan Dhan accounts.
- Discussions around customized credit products for women and broader financial services.
- Initiatives to activate dormant accounts and better integrate them into the financial ecosystem.
These proposals reflect the government’s continued commitment to deepen financial inclusion and build a more robust, accessible financial network for all citizens.
Common Misconceptions About Jan Dhan Accounts
Myth: Accounts with No Transactions Will Be Closed
Fact: The government hasn’t ordered mass closure of inactive Jan Dhan accounts; rather, banks are encouraged to engage account holders and update KYC so that benefits can continue.
Myth: Only Poor People Can Open the Account
Fact: Any Indian citizen who satisfies basic eligibility criteria can open a Jan Dhan account, not just low-income individuals.
Impact of Jan Dhan Yojana
Massive Financial Inclusion
Pradhan Mantri Jan Dhan Yojana (PMJDY) ne Bharat mein financial inclusion ko badhava dene mein mahatvapurn bhoomika nibhayi hai. Is yojana ke madhyam se desh bhar mein crores of bank accounts khole gaye hain, jisse banking services un logon tak pahunchi hain jo pehle formal financial system se jude nahi the.
PMJDY ke through underserved aur low-income communities ko banking, savings, digital payments, insurance aur anya financial services tak pahunch banane ka avsar mila hai. Bank account ki suvidha hone se log apni savings ko formal banking system mein rakh sakte hain aur eligible government benefits ko direct account mein receive kar sakte hain.
Is bade star par banking access ne Bharat mein financial exclusion ko kam karne mein madad ki hai. Saath hi, formal financial services tak pahunch badhne se logon ke liye apne paison ko surakshit tareeke se manage karna aur financial opportunities ka labh uthana aasaan hua hai.
Empowering Women
Pradhan Mantri Jan Dhan Yojana ne women's financial inclusion ko badhava dene mein bhi mahatvapurn bhoomika nibhayi hai. PMJDY ke tahat khole gaye bank accounts mein mahila account holders ki bhi badi hissedari hai, jo formal banking system mein unki badhti participation ko darshati hai.
Bank account hone se mahilaon ko apni savings manage karne, digital payments ka upyog karne aur eligible government benefits ko directly receive karne mein adhik suvidha mil sakti hai. Isse unki financial awareness aur apne paison se jude faislon mein participation badhne ka avsar milta hai.
Is tarah PMJDY sirf banking access badhane tak seemit nahi hai, balki gender financial inclusion aur women’s economic participation ko majboot karne mein bhi sahayak hai. Financial services tak behtar pahunch mahilaon ko adhik financial independence ki disha mein aage badhne ka avsar de sakti hai.
Digital Payments & Formal Economy
Jan Dhan accounts ne JAM (Jan Dhan-Aadhaar-Mobile) framework ke saath milkar Bharat mein digital financial services aur government benefit transfers ko badhava dene mein mahatvapurn bhoomika nibhayi hai. Is framework ke madhyam se eligible beneficiaries ke bank accounts ko Aadhaar aur mobile connectivity ke saath integrate karke payments ko adhik efficient banane ka prayas kiya gaya hai.
Direct bank transfers ke karan sarkari subsidies aur welfare payments ko beneficiaries tak seedhe pahunchana aasaan hua hai. Isse cash-based distribution par nirbharata kam karne, payment records maintain karne aur transparency badhane mein madad mil sakti hai. Government payments mein intermediaries ki bhoomika kam hone se leakage ko reduce karne ka bhi uddeshya raha hai.
Jan Dhan accounts ke madhyam se log digital payments, banking transactions aur formal financial services ka upyog kar sakte hain. Is tarah PMJDY aur JAM framework ne underserved populations ko formal economy se jodne aur financial inclusion ko aage badhane mein yogdan diya hai.
FAQ
What is the main objective of PM Jan Dhan Yojana?
The primary goal is to bring every Indian into the formal banking system by offering zero-balance bank accounts and access to financial services like savings, credit, insurance, and pension.
Who can open a Jan Dhan account?
Any Indian citizen aged 10 or above without an existing bank account can open one. NRIs are not typically eligible.
What insurance benefits do I get?
Jan Dhan accounts include accidental insurance (up to ₹2 lakh) and life insurance for eligible holders through linked RuPay cards.
How does Jan Dhan help with government schemes?
Jan Dhan accounts serve as the banking gateway for Direct Benefit Transfers (DBT) of subsidies and welfare payments, ensuring efficiency and transparency in fund transfers.
Do I need to maintain a minimum balance?
No — PMJDY accounts require zero minimum balance, making them accessible to all.
Conclusion
PM Jan Dhan Yojana remains a cornerstone of India’s financial inclusion strategy in 2026. It empowers citizens with accessible banking, insurance, credit, and welfare transfer mechanisms. With the Budget 2026 focus on expanding credit and insurance through Jan Dhan accounts, the scheme is poised to deliver even greater socio-economic impact in the years ahead.
Write a comment